
Understanding The Contract Before You Make An Offer
Every condition, explained in plain English.
Making an offer on a court-ordered sale in British Columbia involves the same contract conditions as any real estate purchase, plus additional layers specific to the court process.
Most buyers have never had someone walk through what each clause actually means.
This page does exactly that.
Read through the conditions below, understand what you are agreeing to, and reach out to Woody with any questions before you make an offer.
What These Conditions Are & Why They Matter
Buying a home isn't just about agreeing on a price.
Subject conditions protect you by giving you time to investigate the property, arrange financing, review important documents, and make sure you're comfortable moving forward before becoming legally committed.
Once a condition is removed, that protection is gone. Understanding what each condition means is one of the most important parts of making an informed offer.
These explanations are intended to help you understand common subject clauses and are not legal advice.
General Information Only
The Conditions - Explained
Financing
-
Subject to the buyer arranging suitable bank financing in the form of a new first mortgage at current market rates on or before [date]. This condition is for the sole benefit of the Buyer.
-
This gives you time to get your mortgage approved before the deal is locked in. If your bank does not approve your financing by the deadline, you can walk away and your deposit is returned. The seller cannot use this clause against you - it exists entirely for your protection as the buyer.
Home Inspection
-
Subject to the Buyer, on or before [date], at the Buyers expense, obtaining and approving an inspection report against any defect whose cumulative cost of repair exceeds [amount] and which reasonably may adversely affect the property's use or value. The seller will allow access to the property for the purpose on reasonable notice. This condition is for the sole benefit of the Buyer.
-
You hire a home inspector at your own cost. If they find problems where the total repair cost exceeds the agreed threshold, you can cancel the deal or return to negotiate. The seller must give the inspector reasonable access to the property. This protection is yours, not the seller's.
Fire / Property Insurance
-
This offer is subject to the Buyer obtaining approval for fire/property Insurance, satisfactory to the buyer on or before [date]. This condition is for the sole benefit of the Buyer.
-
You need to confirm you can actually get home insurance on this property before the deal closes. Some properties - older homes, rural properties, unique structures - can be difficult to insure. If you cannot get coverage at terms you are comfortable with, you are not locked into the purchase.
Property Disclosure Statement
-
Subject to the Buyer on or before [date] approving the Property Disclosure Statement dated with respect to the information that reasonably may affect the use or value of the property. If approved, such statement will be incorporated into and form part of the contract. This condition is for the sole benefit of the Buyer.
-
The seller fills out a form declaring everything they know about the property's condition - past repairs, known defects, issues with the structure or systems. You review it and decide if you are comfortable. Once you approve it, it becomes part of your binding contract.
-
In many court-ordered sales, the party with conduct of sale is a lender or an estate -- not the original owner. They may have limited knowledge of the property's history. This is something Woody discusses with every buyer upfront so there are no surprises before conditions are waived.
Property Purchase Tax
-
The Buyer is aware that there is a 1% property purchase tax on the first $200,000.00 and 2% on the Balance.
-
This is BC's Property Transfer Tax -- a government tax paid when purchasing property in British Columbia. The rate is 1% on the first $200,000 of the purchase price, then 2% on everything above that amount. It is paid at closing through your lawyer or notary and is separate from your down payment. First-time home buyers may qualify for a full or partial exemption - ask your notary or lawyer whether you qualify before closing.
Septic Tank
-
Seller warrants that he will have the septic tank pumped and inspected at his expense by [date]. This condition is for the sole benefit of the buyer.
-
If the property uses a septic system, the seller agrees to have it professionally pumped and inspected before closing - at their cost. This gives you confirmation the system was in working condition at the time of sale.
-
In a court-ordered sale, the party responsible may be an estate or a lender who has not occupied the property. Whether this warranty can be made - and by whom - is something Woody works through with all parties before offers are submitted.
Title Search
-
Subject to the buyer on or before [date], searching and approving title to the property against the presence of any charge or other feature, whether registered or not, that may reasonably affect the property's use or value. This condition is for the sole benefit of the buyer.
-
Before the deal is final, your lawyer or notary runs a title search to check for anything attached to the property - liens, unpaid debts, easements, rights of way, or other legal claims. If something turns up that you are not comfortable with, you have the right to walk away. In court-ordered sales, title is often cleared through the court process, but you still have your own lawyer or notary review it independently.
Water Supply
-
Subject to the Buyer, at the Buyers expense, receiving and being satisfied with a report concerning the quantity and quality of the water supply by [date]. This condition is for the sole benefit of the Buyer.
-
If the property uses a well or non-municipal water source, you have the right to have the water tested and the supply assessed before committing. You pay for the test. If the water quality or quantity does not meet your requirements, you can exit the deal. This clause is particularly relevant for rural properties throughout the Thompson-Okanagan region.
Insurance (Comprehensive )
-
Subject to the Buyer obtaining approval, on or before [date], from a licensed insurer for property coverage (including, without limitation, fire, earthquake and flood coverage) and liability insurance for the Property on terms and at rates satisfactory to the Buyer in its sole discretion. This condition is for the sole benefit of the Buyer.
-
This is the more detailed version of the insurance condition. It specifically requires fire, earthquake, and flood coverage - not just basic property insurance. Given wildfire risk and flooding in parts of the Thompson-Okanagan region, confirming full coverage before waiving this condition matters. If you cannot get coverage at rates you find acceptable, you are not locked into the purchase.
Force Majeure
-
If either party, despite their best efforts, is delayed from completing this transaction or other transactions or unable to obtain insurance that this transaction is dependant on to complete due to: acts of God, fire, landslide, flood, tempest, washout, disaster, earthquake, storm, epidemic, quarantine, or civil disturbance (an Event) then the affected party's solicitor shall provide notice (the Force Majeure Notice) to the other party or such party's solicitor or notary of such event no more than three (3) business days prior to the Completion date and no later than noon on the Completion Date. Upon receipt of the Force Majeure Notice, the Completion, Possession, and Adjustment Dates shall be extended one time to the first business day which occurs thirty (30) days following the Force Majeure Notice and time shall remain of the essence.
-
If something completely outside anyone's control - a natural disaster, wildfire, flood, earthquake, pandemic, or civil emergency - prevents the deal from closing on time, neither party is penalized. The affected party's lawyer must give notice within 3 business days before the closing date, and no later than noon on closing day. All key dates then automatically push out by 30 days. This is a one-time extension only. Time still matters - the delay is structured and limited, not open-ended.
Legal Advice
-
Subject to the Buyer obtaining and approving independent legal advice regarding any issues with this offer of purchase and sale including a title review.
-
This condition gives you time to have your own lawyer or notary review the entire contract before it becomes binding. In a court-ordered sale especially, this step is not optional - the process is more complex than a standard purchase, and having qualified legal counsel review everything before you waive this condition is strongly recommended.
Title Review (Detailed)
-
Subject to the Buyer searching and approving a current title search including all registered charges on the title. The Buyer acknowledges and accepts that on Completion, the Buyer will receive title containing, in addition to any encumbrance referred to in Clause 22 (TITLE) of this contract, any non-financial charge set out in the copy of the title search result that is attached to and forms part of this contract. Upon request of the Buyer or the Buyer's agent, the Seller will direct the Seller's agent to obtain and provide to the Buyer or Buyer's agent in writing, a copy of the title and any charges on title.
-
A full title search is conducted on the property. Any existing non-financial charges - things like registered rights of way or easements - are identified upfront and become part of your contract. There are no surprises: charges that come with the title are disclosed to you in writing before you commit. On request, the seller's agent provides a full written copy of the title and all registered charges.
The Professionals You Need In Your Corner
A real estate transaction, especially a court-ordered sale, involves more than just you and the seller. Having the right people in place before you make an offer is what separates a smooth process from a stressful one.
A REALTOR® Who Knows The Process
Not every REALTOR® has experience with court-ordered sales. The process involves additional steps, more parties, and court oversight that most agents rarely navigate. Working with someone who has handled these transactions before, and who can explain each stage clearly, is not a nice-to-have. It is essential.
A Licensed Home Inspector
A qualified home inspector identifies defects, maintenance issues, and potential problems that are not visible to the untrained eye. In a court-ordered sale, the property may have been vacant or poorly maintained. A thorough inspection before waiving your inspection condition is money well spent.
A Lawyer Or Notary
You need your own independent legal counsel reviewing the contract, the title, and the court order before any conditions are waived. In a standard sale this is strongly recommended. In a court-ordered sale it is critical. Your lawyer or notary is the person who ensures your legal interests are protected at every stage of the process.
A Mortgage Broker Or Lender
Get your financing sorted before you make an offer, not after. Knowing exactly what you are approved for, at what rate, and under what terms removes one of the biggest sources of uncertainty in the process. Court-ordered sales move on specific timelines. Having financing in place from the start keeps everything on track.
An Insurance Broker
Contact an insurance broker early, ideally before you make an offer. Some properties in the Thompson-Okanagan are in areas with elevated wildfire or flood risk, which affects the availability and cost of coverage. Knowing your insurance situation before committing avoids a difficult problem at a stage where your options are limited.
Why The Right REALTOR® Makes The Difference
Court-ordered sales are not handled the same way as a standard listing. There is more coordination, more oversight, and more that can go sideways when the process is not managed carefully.
A REALTOR® who has navigated these transactions before knows how each stage works, what the court expects, and how to keep things moving when complications arise.
What that looks like in practice:
Clear communication with all parties throughout the process, legal counsel, the court, and the buyer
Experience managing offers under court supervision, including how competing offers are handled at the court approval stage
The ability to anticipate problems before they become delays or deal-breakers
A calm, steady approach that reduces uncertainty for everyone involved
Woody Kuraoka has been handling complex real estate transactions across the Thompson-Okanagan for over 18 years. Court-ordered sales, estate sales, and situations where the process matters as much as the price are where his experience is most visible.
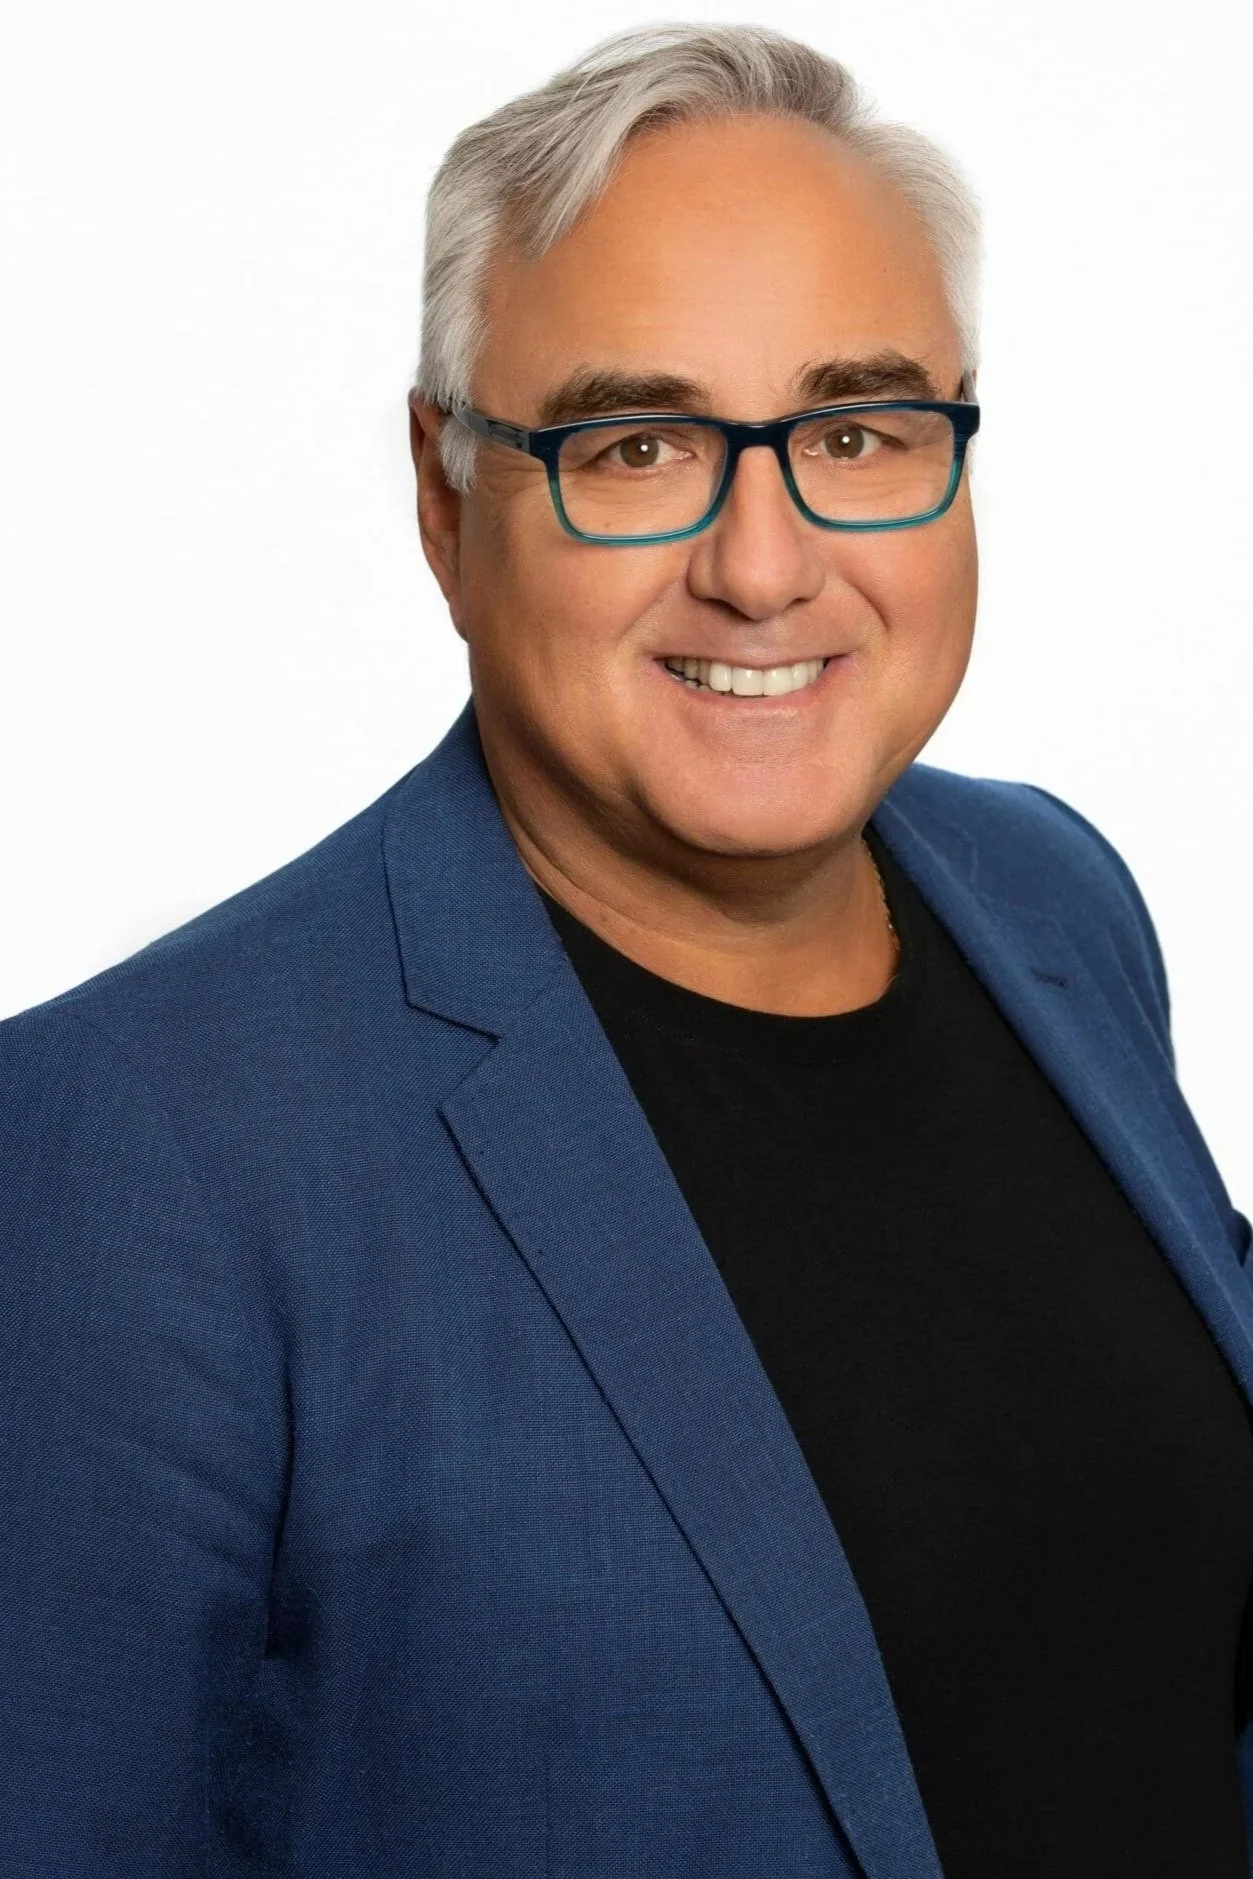
Understanding the contract is the first step. The next step is a conversation with someone who knows this process.
Reach out to Woody directly, or register to receive notification when new court-ordered sale listings become available across the Thompson-Okanagan region.